

OnePay – Mobile Banking
by ONE Finance, Inc.
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
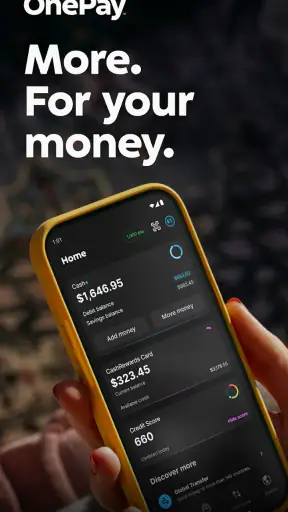
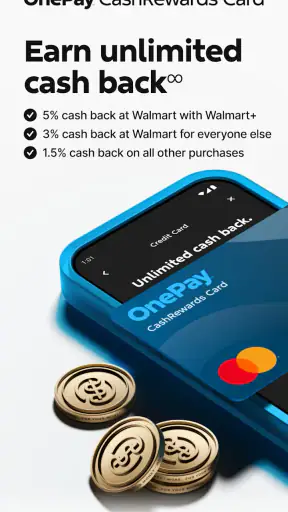
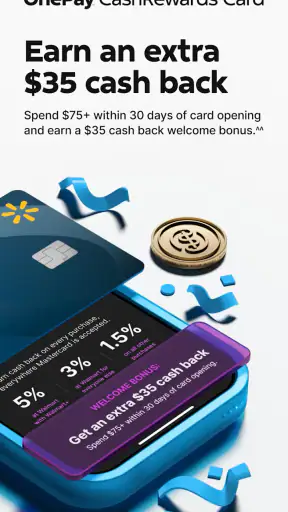
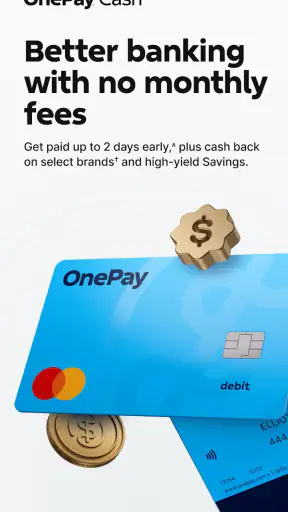
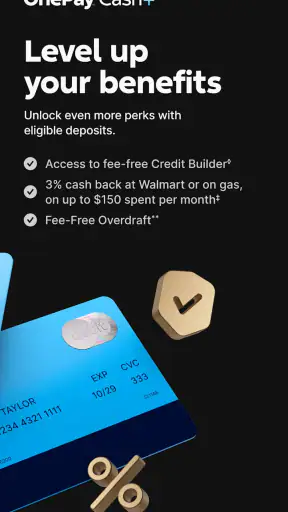
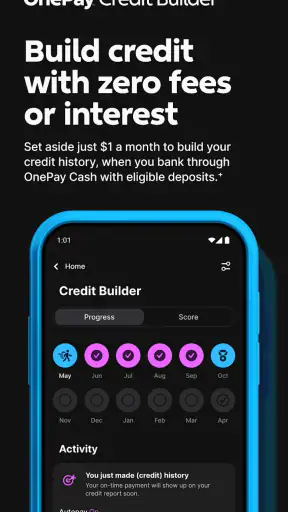
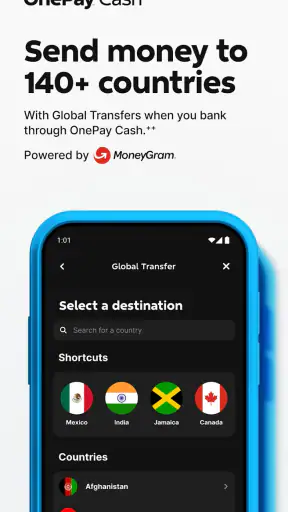
 Analysis by Getfullapps
Managing money on a phone only works when the screen, language, and navigation stay understandable in the moments when you actually need them. I spent time looking at OnePay – Mobile Banking from that practical angle: not just whether it can sit in a finance folder, but whether it feels usable when your attention is divided, your vision is tired, or you need to check something quickly. It is a free finance app from ONE Finance, Inc., positioned around banking, credit, and related money tasks.
My overall impression is that OnePay is most appealing to people who want everyday financial activity gathered in one mobile experience rather than spread across separate banking and credit tools. Its public reception is strong, with a 4.8 average from around 184 thousand ratings, and it has passed five million installs. Those figures do not replace personal testing, but they do suggest that the app has reached a substantial audience.
How OnePay feels to read and navigate
The first thing I noticed is how important the app’s information hierarchy becomes. A finance app has to make balances, transactions, account actions, and credit-related information feel distinct. When those areas are clearly separated, I can glance at the screen and understand where I am. That matters more here than visual decoration: a banking interface should reduce hesitation, especially when I am checking a payment or trying to find a recent purchase.
OnePay’s appeal is its attempt to bring banking and credit into the same destination. In ordinary use, that can reduce the mental switching involved in opening one app for spending and another for credit information. For someone who checks money several times during the day, fewer context changes can make the routine feel less tiring. I would still take a moment after setup to learn where each major action lives, because familiarity is what turns a finance app from merely available into genuinely quick.
Readability is not only about whether text looks large enough. It is also about whether labels explain themselves, whether figures are grouped sensibly, and whether a warning or confirmation is easy to distinguish from a normal account update. I found that the best way to use OnePay is to slow down during the first few sessions, identify the areas I expect to revisit, and then rely on that learned path instead of exploring while distracted.
That approach is particularly useful for people who are less comfortable with mobile banking. A new user may not know whether a card-related action, a transfer, or a credit item belongs under the same menu. The app’s combined focus is convenient, but it also means there is more financial information to interpret than in a very narrow single-purpose wallet. I would recommend completing the initial setup when calm, not while standing in a checkout line.
Why the combined money view can help
One practical strength is the possibility of seeing everyday banking and credit activity as parts of one financial routine. I can imagine opening the app before paying a bill, checking available money, then reviewing whether a recent purchase has appeared correctly. That sequence is more useful than simply having a list of isolated features because it supports a decision: can I afford this now, and does the account activity match what I expected?
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
There is also a subtle benefit for people who find repeated app switching difficult. Moving between multiple interfaces can create errors, particularly when the designs use different terms for similar actions. Keeping related tasks together may make the process easier to remember. The trade-off is that a broader app can feel busier than a basic balance checker, so OnePay is better suited to someone who wants an expanding financial workspace than to someone seeking the smallest possible interface.
I would not treat the strong rating as proof that every screen will suit every reader. People differ in eyesight, attention, language comfort, and familiarity with financial vocabulary. My useful test is simple: can you find the balance, recognize a transaction, and locate help or account controls without guessing? If those actions feel clear on your device, the app is likely to fit your routine. If they feel crowded or ambiguous, a simpler banking product may be more comfortable.
Motor, sensory, and cognitive considerations
Mobile finance tasks often involve precise tapping: selecting an account, opening a transaction, confirming an action, or moving through a form. That makes motor comfort important. I prefer to use OnePay with deliberate taps rather than rapid swipes, especially around actions that could change account activity. Users with limited dexterity may find a short session easier than trying to complete several unrelated tasks at once.
A useful personal workflow is to separate checking from acting. I first open the app to review the balance or transaction, then pause before selecting any button that could initiate a financial action. This is not an app feature; it is a safety habit that reduces accidental taps and gives me time to read the confirmation. It also helps when hand movement is less predictable or when the phone is being used one-handed.
For sensory access, screen glare and lighting make a real difference. A dark or reflective environment can make account figures harder to read, while a bright outdoor setting can wash out interface details. I would adjust the phone’s display settings and choose a comfortable viewing angle before making an important transaction. I would also avoid relying on memory when comparing amounts: read the figure directly, then verify the surrounding label and transaction context.
People with visual processing difficulties may benefit from a slower, consistent route through the app. Rather than scanning the entire screen, I would look for one task at a time: balance first, then activity, then the specific item that needs attention. This reduces the chance of confusing a current balance with a credit figure or a pending-looking item with a completed one. The combined banking-and-credit approach is helpful when understood, but it rewards careful reading.
For users who depend on spoken assistance or other device-level accessibility tools, the practical question is how well the app behaves with the settings already used on the phone. I would not assume that every control, label, or financial status will be equally easy to interpret through assistive technology. Before moving a primary banking routine into OnePay, I would install it on the device that person actually uses and test the specific actions they need, such as reading a balance and reviewing a transaction.
Cognitive load deserves equal attention. Financial language can be stressful even when the interface is technically tidy. OnePay may be convenient for bringing several money topics together, but that also asks me to distinguish between banking information and credit information. I find it easier when I decide in advance what I am checking. “Review today’s purchases” is a clearer goal than “look around the account,” and it keeps the session focused.
A realistic everyday routine
Imagine getting a message that a household payment is due while you are commuting. I would wait until I could hold the phone securely, open OnePay, check the relevant balance, and review recent activity before taking action. If the screen is difficult to read in the moving environment, I would postpone the payment rather than rush. The app can support the check, but the surrounding situation still determines whether using it is sensible.
Later, at home, I might use a quieter session to review the transaction and confirm that the account activity makes sense. This two-stage routine is one of my strongest recommendations: use the app for quick awareness when needed, but reserve important decisions for a stable setting. It is more inclusive than assuming every user can comfortably complete a full financial task in public, noisy, bright, or physically awkward conditions.
Another helpful habit is to keep a short personal vocabulary for the app. I mentally separate “money available for daily use,” “recent activity,” and “credit information,” even if the app presents them close together. That simple distinction can help users who are new to financial apps or who become overwhelmed by multiple figures. It also makes it easier to explain the workflow to a family member without handing over control of the account.
Situations where access becomes harder
OnePay is designed for phone-based financial management, so access depends on the phone itself. A small screen, a damaged display, weak battery, noisy surroundings, or an unreliable connection can turn a simple check into a frustrating task. I would not choose it as the only way to manage money for someone who regularly needs a larger display, in-person assistance, or a desktop workflow.
Public use creates another challenge. Banking information is private, and a crowded train or shared room may make it uncomfortable to read balances or transaction details. This is not a flaw unique to OnePay, but the app’s usefulness should be judged alongside the environment in which it will be used. For quick confirmation, a brief glance may be reasonable; for reviewing several entries, I would wait for privacy.
People with hearing-related needs should not be expected to rely on audio cues alone, and people with vision-related needs should not be expected to rely on visual cues alone. The safest approach is to check how the app’s important messages appear through the phone’s available settings and to confirm that the information is understandable in the user’s preferred mode. I would especially test sign-in, transaction review, and confirmation screens before depending on the app for urgent tasks.
Older users or people who are anxious about digital banking may also experience friction during setup. Even when an app is free and aimed at a broad audience, financial terminology can make the first session feel demanding. I would sit with the user, let them control the phone, and write down the few navigation steps they actually need. That preserves independence better than taking over every action.
Remaining barriers and sensible alternatives
The main limitation I see is that convenience and concentration pull in opposite directions. Combining banking and credit can reduce app switching, but it can also create more information to sort through. Someone who wants a basic account view with almost no extra context may prefer a traditional bank app that focuses only on their existing account. Someone who wants credit tools and everyday banking in one place may find OnePay more coherent.
There is also a difference between a mobile-first experience and a full-service financial relationship. A phone is excellent for checking activity while away from home, but it is not always the best environment for comparing documents, studying a complicated financial decision, or helping another person with limited vision. In those situations, a larger screen or human support may be better. I would use OnePay as a practical daily tool, not as a reason to abandon every other way of reviewing finances.
Users should also think about trust and habits before consolidating money tasks. A single app can simplify routines, but it can also make the app more central to daily finances. I recommend starting with low-risk activities such as viewing information and learning the layout, then deciding whether it feels comfortable enough for more active use. This staged approach is especially valuable for anyone who has previously made mistakes in mobile banking.
The app is free, which lowers the barrier to trying it, and it is rated for Everyone. It supports a wide intended audience, but those labels do not tell me whether the experience will be comfortable for a particular person’s vision, dexterity, reading style, or assistive setup. I would treat the age rating as general guidance, not as a guarantee of effortless accessibility.
ONE Finance, Inc. continues to develop the app, with version 5.80.0 identified as the current version and support for Android 7.1 and later. That broad device compatibility may help people using older phones, although an older device can still affect performance and readability. Before switching completely, I would test the specific handset, display, and accessibility settings used every day.
My inclusive verdict
After using it as a finance app rather than judging it only by its short “OnePay” store label, I see a product aimed at making banking and credit feel closer together. I like the potential reduction in app switching, the usefulness of a single routine for checking money, and the fact that the app is free to try. The high average rating and more than five million installs show that many people have found value in that direction.
My recommendation comes with a clear condition: take time to learn the layout and test it in the situations that matter to you. If you have good screen access, prefer managing money from a phone, and want banking and credit information in one place, OnePay is worth considering. It can be especially useful for a person who wants quick awareness during the day but is willing to reserve important actions for a calm, private moment.
I would be more cautious for anyone who needs a very sparse interface, depends heavily on a particular assistive workflow, or prefers face-to-face help and large-screen document review. In those cases, a simpler bank-specific app or another support channel may be a better primary option. The most inclusive choice is the one that lets you verify financial information confidently, without rushing or guessing.
For me, OnePay works best when treated as a focused tool: open it with a clear purpose, read the labels around every figure, separate checking from acting, and use a comfortable environment for anything consequential. That combination of app design and personal routine matters more than a feature list. If that approach matches the way you manage money, this finance app offers a practical and approachable place to start.
Pros
- User-friendly interface for easy navigation.
- Supports multiple account management.
- Real-time transaction notifications.
- Secure login with biometric authentication.
- No hidden fees for transactions.
Cons
- Limited customer support hours.
- Occasional app crashes reported.
- Some features require a strong internet connection.
- Not available in all regions.
- Limited integration with third-party apps.
FAQs for OnePay – Mobile Banking
What services does OnePay – Mobile Banking offer?
OnePay provides a range of banking services, including balance checks, fund transfers, bill payments, and mobile top-ups. It also offers features like transaction history, budget tracking, and financial management tools. Users can manage multiple accounts and access their banking details securely, making it a comprehensive solution for digital banking needs.
Is OnePay secure to use for online banking?
Yes, OnePay employs advanced security measures to protect user data. This includes multi-factor authentication, end-to-end encryption, and real-time fraud monitoring. Users can also set up biometric logins, such as fingerprint or facial recognition, to add an extra layer of security to their accounts.
Can I access my account from multiple devices?
Absolutely. OnePay allows users to access their accounts from multiple devices, including smartphones, tablets, and computers. The app syncs seamlessly across devices, ensuring that your financial information is up-to-date and accessible wherever you are, while maintaining robust security protocols.
Are there any fees associated with using OnePay?
OnePay is free to download and use for basic services, such as checking balances and viewing transaction history. However, certain transactions like international transfers or expedited payments might incur fees. Users should review the app's fee schedule in the settings or help section for detailed information.
Does OnePay support international transactions?
Yes, OnePay supports international transactions. Users can send and receive money globally, though fees and exchange rates may apply. It is advisable to check the app for specific countries supported and any associated costs before initiating an international transfer to ensure transparency and avoid unexpected charges.

OnePay – Mobile Banking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@onefinance.com, visit https://www.onefinance.com, or review their https://hello.one.app/e/privacy-notice.










